Dividends and interest income — 98 countries
Recover foreign dividend tax. No success fee — the refund stays yours.
Import a broker statement or type the figures in. See what was withheld above your treaty rate, then generate the filing document your reclaim takes.
Information tool, not tax advice. Calculations use OECD treaty rates updated 2026.
OECD treaty ratesBilateral DTT tables
ECB & other central bank ratesHistorical rates by payment date
EU PSD frameworkParent-Subsidiary Directive
National tax authoritiesSource-of-record citations
Run the full calculation
See how much excess withholding tax you may be able to recover.
Built by former Big Four and global consultancy specialists in tax technology and cross-border tax · Every rate cited to its official source · An information tool, not tax advice.
What you get
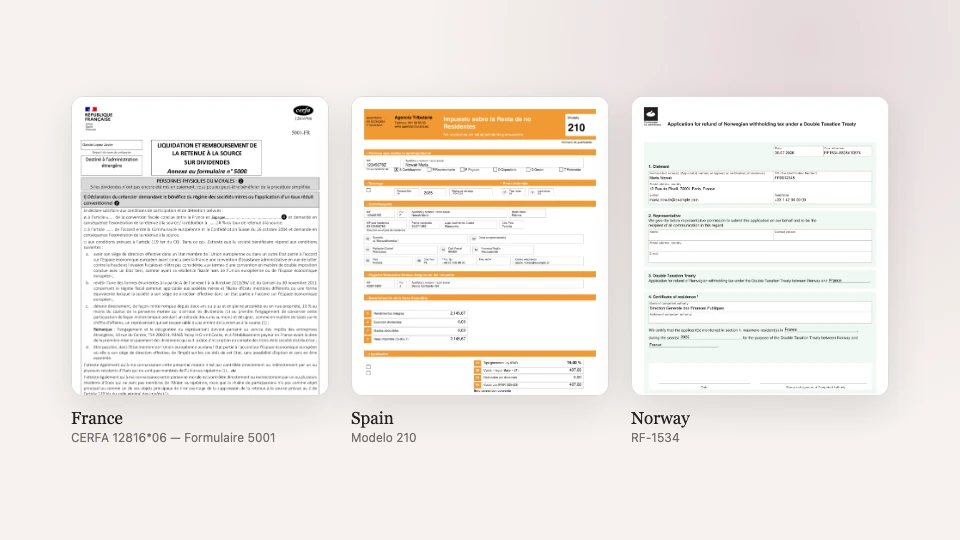
Review the generated document
These examples are output from our generator. Each form guide identifies the document as an official form, a worksheet or a request letter.
- Official formjurisdictions
- 25
- Worksheetjurisdictions
- 15
- Request letterjurisdictions
- 8
Why money stays unclaimed
Three reasons investors leave money behind
The European Commission estimates €8.4 billion in cross-border tax relief goes unclaimed every year.
Forms are country-specific
Each country has its own filing route. We label the output as an official form, a worksheet, or a request letter.
Treaty rates change each year
Withholding caps depend on the bilateral tax treaty between your residence and the dividend source. We use the OECD-published rates current to the tax year you select.
Deadlines are unforgiving
Most refund windows close two to four years after payment. Miss the date and the over-withheld tax stays with the foreign treasury.
The process
Three steps from dividend to refund
- 01
Import a statement or enter the figures
Import your broker's export (DeGiro, Interactive Brokers, Trade Republic, Trading 212, Nordnet and 11 more), or type in source country, residence, gross amount and payment year. Enter exact dates when the filing deadline depends on them. No broker login either way.
- 02
See the recoverable amount instantly
We apply the treaty rate, subtract what was withheld, and show the gap you can reclaim — with the data source cited inline.
- 03
Prepare the country filing document
Generate the supported document with your figures. Check its filing status and submit through the required channel.
The hidden cost of withholding tax
Billions in unclaimed tax relief
Every year, billions in legitimate tax relief goes unclaimed due to complex cross-border paperwork.
€8.4B
EU unclaimed relief
Annual tax relief that goes unclaimed according to European Commission estimates
European Commission20 points
Swiss dividend over-withholding
Switzerland withholds 35% on dividends. Most treaty residents owe 15%, and the 20-point difference is reclaimable.
Swiss Federal Tax AdministrationWhat the gap costs by staying unclaimed
Switzerland withholds 35% on dividends where most treaty residents owe 15%. The 20-point difference stays with the Swiss treasury, and so does everything it would have earned. Move the sliders to change the example.
Unrecovered tax each year
€300.00
Over 30 years, the example portfolio gives up
€28,338.24
Illustrative only. The figure assumes the recovered tax is reinvested every year at the stated return, an assumption rather than a promise, and ignores tax on the reinvested income. It describes the example portfolio above, not anyone's actual holdings.
Calculate your actual refundStatistics are based on publicly available reports from regulatory bodies and industry research.
The research behind the tool
Where every number comes from
Rates, forms and deadlines come from published treaty texts and tax-authority documents, reviewed every tax year. The Sources page links the government publication wherever we hold one.
Double tax treaties
Treaty and statutory withholding rates for 98 source countries, resolved against the payment date and reviewed every tax year.
See the sourcesRefund claims
Sign-and-submit official forms for 25 jurisdictions, out of 38 with a generated filing document.
Browse the formsForeign tax credits
Foreign tax credit computations for 16 residence countries, filed directly on the UK SA106 and the French 2047.
EU FASTER directive
Member states must have FASTER in national law by 31 December 2028 and apply it from 1 January 2030 at the latest. A single EU-recognised digital residence certificate issues within 14 days, and the quick refund lands within 60 days.
Directive (EU) 2025/50Reclaim deadlines
Reclaim windows for 43 countries, from Luxembourg's one year to Taiwan's ten, each computed on its own statutory basis. 29 run from the end of the payment year, 10 from the payment date itself, and the US from the later of filing plus three years or payment plus two.
See every deadline- EU-hosted, GDPR-compliant data
- No broker login required
- Official forms, worksheets and letters
- 98 countries covered
Questions